A perspective piece from The Listening Market
Money has always been complicated in the same way. Not because the maths is hard, though for some people it is, but because managing it well requires a combination of habits that most humans find difficult to sustain. Tracking spending. Planning ahead. Resisting impulse purchases. Understanding financial products that seem designed to confuse. For decades, the advice was the same. Make a budget. Stick to it. Save first. Spend what is left. Simple in theory, elusive in practice.
Artificial intelligence is changing the practical experience of managing money, not by making people more disciplined but by reducing the number of decisions they have to make. The shift is quiet. There is no single product or moment that announces it. But across banking apps, budgeting tools, investment platforms, and even tax preparation software, AI is doing the work that used to require spreadsheets, self-control, and a reasonable amount of anxiety.
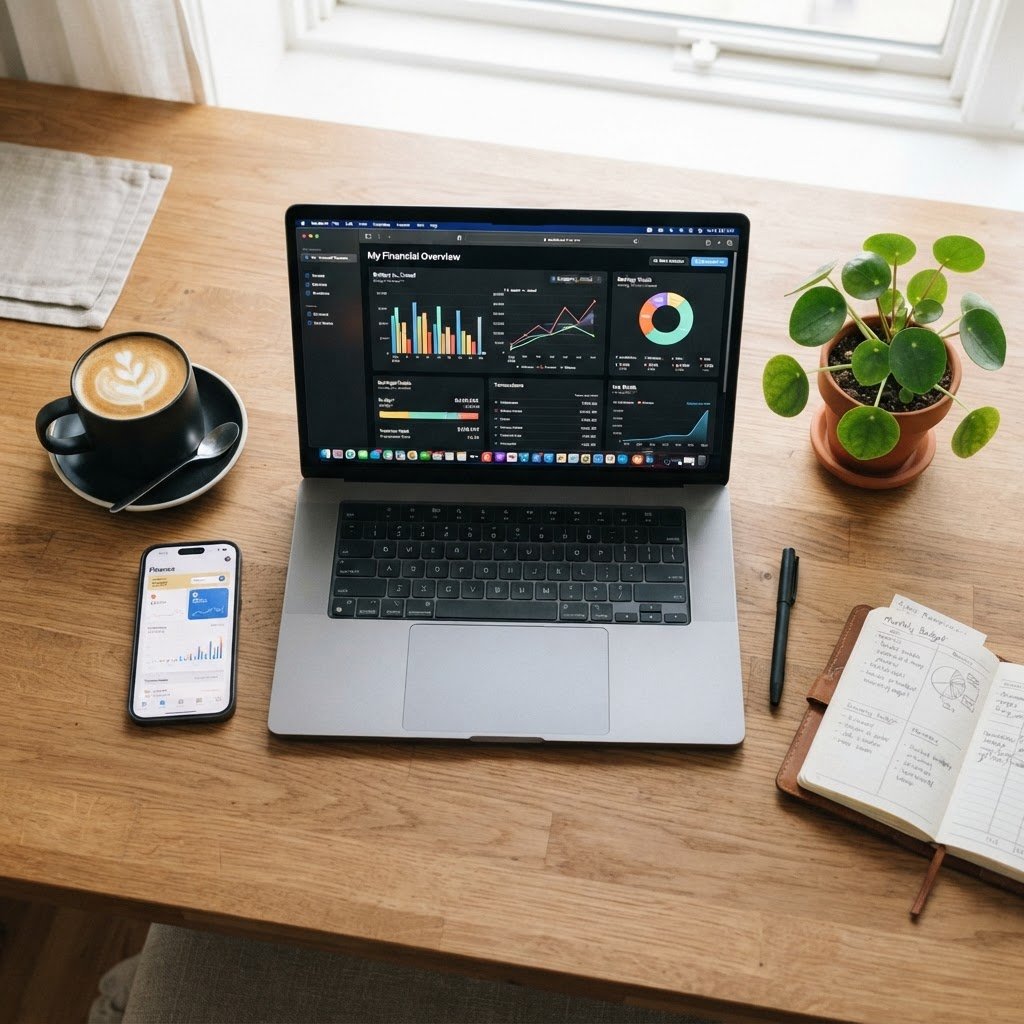
The most visible change is in everyday banking. Major banking apps now use AI to categorise spending automatically, recognise patterns, and flag unusual transactions in real time. What used to require manually logging every purchase into a spreadsheet is now done in the background. A person opens their app and sees not just a balance but a breakdown. How much went to groceries. How much to transport. How much to subscriptions they forgot they had. The information was always there, buried in transaction histories. AI makes it visible.
Beyond categorisation, some platforms are moving toward active assistance. Apps can now send alerts when spending in a particular category is trending higher than usual. They can suggest moving money into savings when the account balance exceeds a typical threshold. They can identify recurring charges that look like forgotten subscriptions and prompt the user to review them. None of these actions are revolutionary on their own. Together, they represent a shift from passive financial tools to active ones, tools that do not just store information but act on it.
The budgeting space has been similarly transformed. Traditional budgeting required a person to set limits, track expenses, and compare the two regularly enough to course-correct. It worked for the sort of person who enjoys spreadsheets. For everyone else, it lasted about three weeks. AI-assisted budgeting tools take a different approach. Instead of asking the user to build a budget from scratch, they analyse past spending and propose one. Instead of requiring manual tracking, they pull data from linked accounts automatically. Instead of waiting until the end of the month to show where things went wrong, they provide real-time feedback as spending happens.
The result is not perfect budgeting, but it is a meaningful improvement over the default, which for many people is no budgeting at all. The key insight is that AI does not need to make people better at managing money. It needs to make managing money easier, so that doing the right thing requires less effort than doing nothing.
Investing has been another area of significant change. Robo-advisors, which use algorithms to build and manage investment portfolios, have been around for over a decade. What is newer is the way AI is being used to personalise investment strategies, assess risk tolerance through conversational interfaces, and provide explanations that do not require a finance degree to understand. A person who would never sit down with a financial advisor can now open an app, answer a few questions, and have a portfolio recommended to them within minutes. The quality of the advice is not equivalent to a human advisor in all cases, but the accessibility is incomparable.
The democratisation effect is real. Financial advice has historically been available to those who could afford it. People with significant assets got advisors. Everyone else got general rules and a pamphlet. AI tools are not a perfect substitute for personalised human advice, particularly for complex situations involving tax planning, estate management, or unusual circumstances. But for the majority of people whose financial needs are relatively standard, the gap between what is available to the wealthy and what is available to everyone has narrowed considerably.
Tax preparation is another area where AI is reducing friction. Tax software has been using forms and logic for years, but newer versions incorporate AI to identify deductions, flag errors, and guide users through the process with conversational prompts. For people with straightforward tax situations, the experience has gone from hours of anxiety to a relatively painless session with an app. For those with more complex situations, the tools serve as a first pass, reducing the time and cost of working with a professional.
Savings automation is perhaps the most practical application. AI tools can analyse spending patterns and identify amounts that can be safely moved to savings without disrupting the person’s cash flow. Some apps round up purchases and invest the difference. Others use algorithms to time transfers for when the account is likely to have a surplus. The psychology behind this is sound. Saving money is easier when it happens automatically, without requiring a decision each time. AI makes it possible to automate savings in a way that adapts to changing circumstances rather than relying on a fixed monthly transfer.
There are legitimate concerns. Privacy is the most obvious. Giving an AI tool access to financial data means trusting a company with detailed information about every transaction. Security breaches are a risk, and the more integrated these tools become, the more damaging a breach could be. There are also questions about bias in algorithmic recommendations, particularly in lending and credit scoring, where AI systems can perpetuate existing inequalities if they are trained on biased data.
Transparency is another issue. When an AI tool recommends a financial product, it is not always clear whether the recommendation is based on what is best for the user or what is most profitable for the platform. The potential for conflicts of interest is not new in financial services, but the opacity of AI systems can make it harder to detect. Regulation is slowly catching up, but the pace of development means that consumers must remain cautious about which tools they trust and what permissions they grant.
There is also the risk of over-reliance. AI tools are good at processing data and identifying patterns, but they are not infallible. Market conditions can change in ways that algorithms do not predict. Personal circumstances can shift in ways that automated systems do not detect. The best use of AI in personal finance is as a tool that supports decision-making, not one that replaces it entirely. Understanding the basics of personal finance, how budgeting works, what compound interest means, why diversification matters, remains valuable even when tools handle the mechanics.
Looking forward, the trajectory is clear. AI will become more integrated into financial products, not less. The tools will get better at understanding context, anticipating needs, and providing guidance that feels less like a calculator and more like a conversation. Voice interfaces may allow people to ask questions about their finances in natural language and receive answers in real time. Predictive tools may become sophisticated enough to warn about potential cash flow problems weeks before they occur.
The broader implication is that financial literacy, while still important, may become less about knowing how to do the calculations and more about knowing which questions to ask. A person who understands their own goals and constraints can get more value from an AI tool than someone who simply follows its recommendations without thinking. The human element is not eliminated. It is shifted from execution to direction.
For now, the change is already meaningful. People who never tracked their spending can see it categorised automatically. People who never invested can start with a few dollars and a guided process. People who never budgeted can get one proposed to them based on their actual behaviour. The barrier to doing the basics well has been lowered, and that is enough to make a difference for millions of people who were previously doing nothing not because they did not care, but because it was too hard.
Money will always be a source of stress. AI cannot fix that entirely. But it can make the practical side of managing money less burdensome, and in doing so, it can free up the mental space that people need to make better decisions about the things that matter most.