A perspective piece from The Listening Market
A woman named Elena keeps a note on her fridge that reads, in cheerful handwriting, “spend on what you love, skip what you don’t”. It is a sentence that sounds like a fridge magnet, and it is also, in eleven words, the entire philosophy of the most useful shift in personal finance this decade. For years, saving money meant restriction, tightening, going without. Budgeting apps spoke the language of diets, and like diets, they mostly failed by February. The approach quietly replacing them begins from a different premise: that feeling restricted and saving money are not the same thing at all, and confusing them is expensive.
The distinction matters because most people do not fail at saving due to arithmetic. Give any adult a spreadsheet, and the numbers are not difficult. People fail at saving because saving-as-restriction makes every day a series of small sacrifices, each one a reminder of what a person’s life cannot contain. Systems built out of denial have a known lifespan. The alternative is to organise money so that cutting happens where it costs nothing felt, and spending happens where it buys actual joy, which turns out to be a surprisingly small and specific list.
Find the three or four purchases that carry the happiness
Almost everyone who examines a year of spending finds the same pattern hiding in the totals. Somewhere between five and ten regular purchases deliver an outsized share of the pleasure in the ledger, and everything else is routine. The good coffee from the place with the wide windows. The Saturday football for the parent who watches a child score. The holiday that gets a family through a wet week in July. These are not leaks in a budget. They are the budget, in the sense that matters: the reasons the money is being earned at all.
Keeping those purchases is not a failure of discipline. It is the point of the whole exercise, and naming them explicitly does two useful things at once. It grants permission to spend where spending genuinely pays, which removes the low hum of guilt that colours even the pleasurable purchases. And it exposes everything else in the spending as a candidate for a haircut, not because it is bad but because it was never loved. Nobody ever got to the end of a subscription audit, a phone contract, or a pantry stocktake and found themselves grieving the duplicate streaming service or the third unopened bottle of the same sauce.
Attack the invisible spenders first
The reason money saving has historically felt like deprivation is that most conventional advice targets the visible, pleasurable spend. Skip the coffee, cancel the holiday, do not buy the shoes. But in most households the largest waste sits elsewhere, in what could be called the invisible spenders: recurring costs that were set once, years ago, and have never been asked to justify themselves since.
The invisible spenders have a personality, and it is worth learning to recognise it. They take the form of subscriptions signed up during a free trial and never cancelled, insurance policies that renewed automatically at a higher premium than the year before, a phone plan sized for a usage pattern that ended two handsets ago. They take the form of energy tariffs, interest rates on a mortgage negotiated in a different decade of interest rates entirely, and the sneaky behavioural one, paying for convenience in small unexamined amounts: the delivery fees, the card surcharges now permitted everywhere, the “just this once” taxis.
None of these cuts touch a single moment of felt pleasure, which is why they are the correct first target. A household that recovers eighty dollars a month from its invisible spenders has improved its position without having given up anything it would notice on a Saturday. The advice is dull of, repetitive, and unglamorous. It is also the closest thing in personal finance to a free lunch.
Align the automatic decisions with the real intentions
Restriction-based budgeting fails a second way: it demands constant decisions. Every purchase becomes a small vote about the kind of person one is trying to be, and self-control is a muscle. The modern approach borrows from product design instead of moral philosophy: rather than deciding better every day, arrange the decisions so the good default happens without anyone’s willpower being consulted.
This is why the automatic transfer on payday has become the foundational move of sensible money. Moving savings out of reach on the first of the month, before the spending month begins, converts saving from a monthly act of virtue into a fact of the landscape. The obscene simplicity of the trick is the reason it works: money never seen is never missed, and the month quietly reshapes itself around what remains. The same principle governs the rest of the friction plan. Bulk-buy the household staples that get used anyway, so the weekly shop needs no negotiation. Keep a small set of staples cooked and ready, so the decision between takeaway and the kitchen is not made while tired and hungry. Put a deliberate delay between wanting something online and buying it, whether that means a cart parked for a day or a one-week rule for anything above a set amount, because the delay alone kills most of the wanting.
The deep idea behind all of these, and the reason they belong in a discussion about happiness rather than discipline, is that they respect the evidence on how satisfaction actually works. The most painful restrictions in conventional budgeting are typically on small repeated pleasures, while the biggest gains in contentment come from the large, planned, anticipated experiences. Anticipation is itself a form of consumption: the booked trip, the awaited dinner, the fortnight of looking forward to a concert are purchases of happiness in instalments, paid in advance. A money system built on this knowledge pulls spending toward the anticipated and planned, and away from the impulsive and forgettable, without banning anything.
One account structure that does most of the work
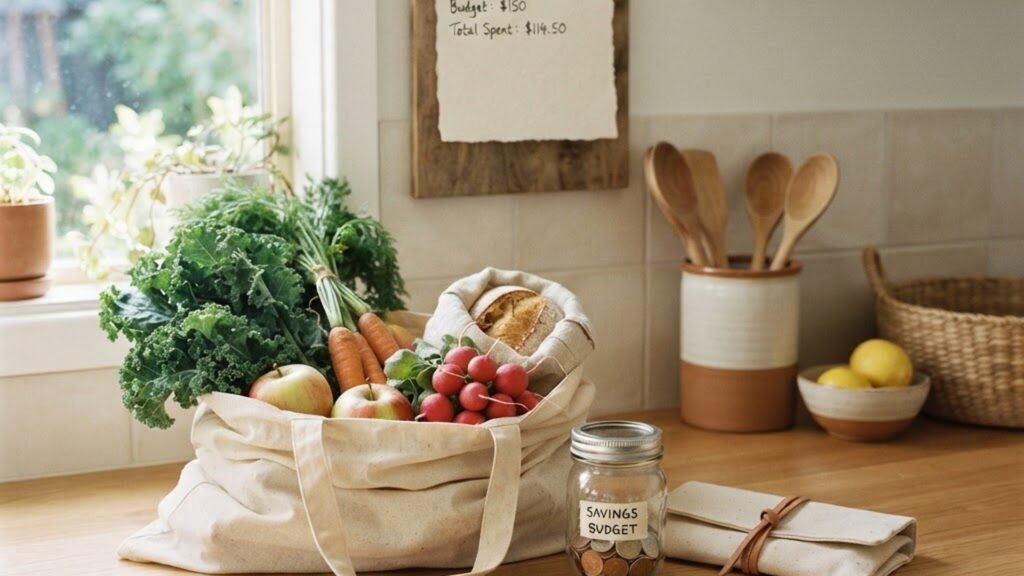
Most people find that the entire philosophy can be implemented, without any app or spreadsheet, by splitting money into three simple containers on payday. One container is the fixed and unavoidable spending, and the invisible spenders, on a schedule, get audited here. The second is the automatic transfer for the future, an amount that left the moment pay arrived, going wherever savings or debt repayment does the most good. The third is everything else, and crucially, this third container is spent with no guilt attached, up to and including the wide-window coffee, because the savings have already left the building.
That final element, guilt-free spending within a structure, is what makes this the opposite of restriction. Deprivation budgeting says no to the present in the name of an abstract future. The container method says yes, freely, to the present built on the remains of a system that already handled the future. The felt difference is enormous. People following the older model describe months of waiting for the diet to end. People following the newer one describe, instead, the quiet disappearance of money anxiety, the peculiar sensation of reaching the end of a month without having thought about money once before payday.
The unglamorous habits that quietly compound
Beyond the containers and the audits sit the small domestic habits that most financial writing overlooks because they do not sound like finance. Maintaining things rather than replacing them, cleaning the filters on the machine, oiling the warm door, getting the piano tuned, flossing the teeth, treating home repairs like urgent correspondence: every one of these converts a small cheap action into the prevention of a large expensive one. Cooking in the tired evenings from the frozen thing made in the un-tired weekend, so the takeaway is a choice rather than a defeat. Buying the good version of the thing bought for keeps: the boots, the jacket, the chair, the mattress, where the cheap version is the expensive one over time because it gets bought three times.
These habits carry almost no feeling of sacrifice, which is exactly the point. They belong to a style of money management in which the savings happen upstream of the moment of spending, so no one ever stands at the till practising restraint. The savings have already been designed into the month, like a well-lit kitchen making the good meal the easy one. The behavioural research has been pointing this way for years: environments beat intentions, and the household is a financial environment before it is anything else.
Small and dull, and it works anyway
There is something almost disappointing about how simple the whole thing turns out to be. No one becomes wealthy from skipping coffee, and very few people are ruined by it either. The outcome of a financial life is determined by the few large automatic arrangements, the recurring contracts, the interest rates, the savings rate, the couple of big purchases per decade, and by the daily texture of small habits either helping or quietly hurting. The coffee is scenery.
Which is the real answer to how people save money without feeling restricted. They stop treating money management as a moral drama of restraint, and they start treating it as infrastructure. They spend freely where it matters, one audited and automated container at a time, and let the automatic system absorb the discipline so the days themselves do not have to. The fridge-magnet sentence, it turns out, was the sophisticated advice all along.
The coffee, of course, stays.