A perspective piece from The Listening Market
The most effective financial habits are not the ones that make headlines. They are the ones so small they barely register as decisions, yet so consistent they gradually reshape a household’s relationship with money. In an era of cost-of-living pressure and endless spending prompts, the people managing best are not pinch-pushing austerity titans of finance. They are ordinary people who have quietly built a series of friction points into their daily routines.
The goal of smart spending is not to stop spending. It is to redirect more of the spending that already happens toward things that actually matter, and to strip out the bits that pass through barely noticed.
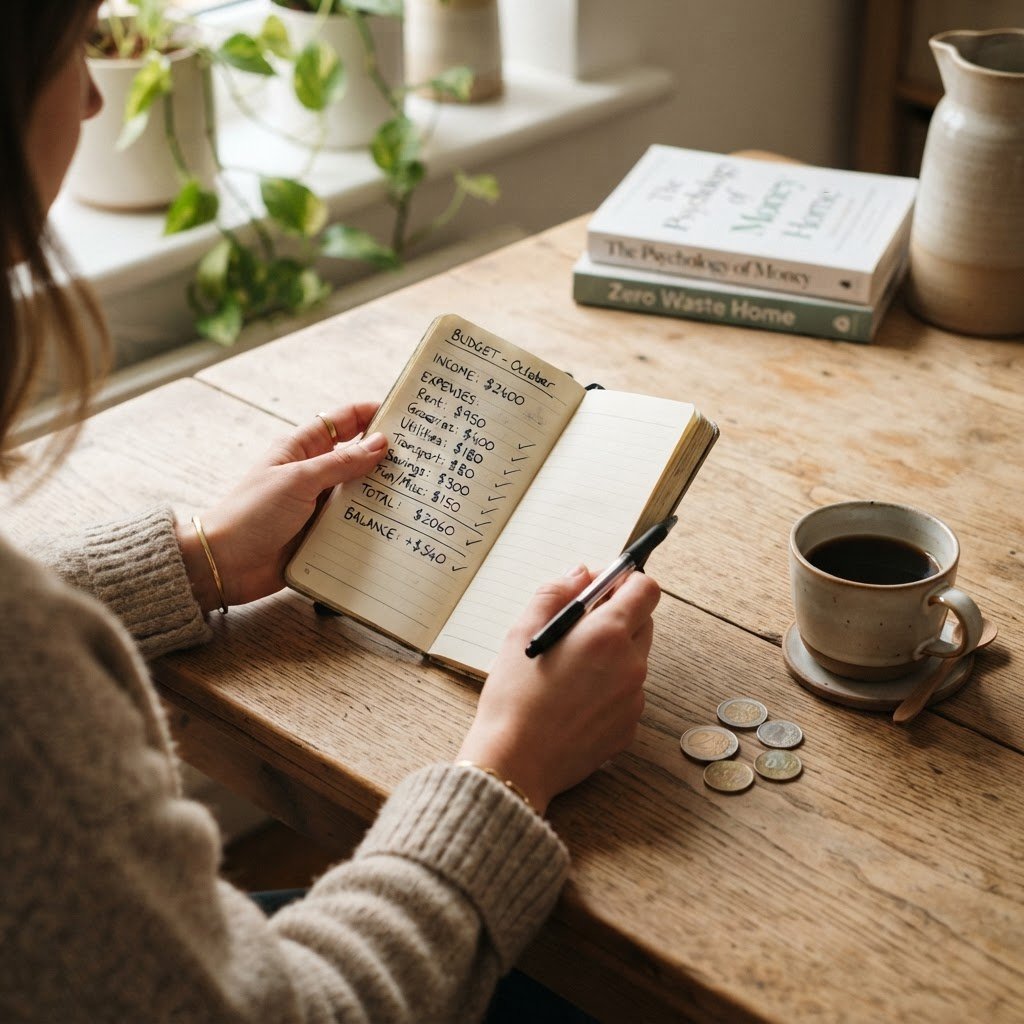
This is a practical philosophy. It draws from behavioral economics, household observation, and the slow accumulating wisdom of people who have quiet household books. Everything below is something real people actually do. Nothing here is a spreadsheet, and nothing here requires a major life restructure.
The Pause That Works
The single most powerful habit in smart spending is not comparison shopping. It is the deliberate insertion of a pause between the impulse to buy and the act of buying.
This is a variation on what behavioral economists call a cooling-off period. Many people adopt versions of it without ever knowing the term. The most common version is the twenty-four-hour rule: anything that isn’t an essential purchase, even groceries that fall outside the list, waits a full day before being bought.
The mechanism is honesty about urgency. The large majority of purchases made in haste don’t survive twenty-four hours of perspective. The jacket that seemed essential at lunch feels non-essential over a quiet morning coffee. The sale-priced device that appeared irreplaceable last night is matched by something cheaper and more suitable by next week.
Some people use longer rules: forty-eight-hour, one-week, or even one month for larger purchases. The principle is the same: create space between want and action, and let the space do the judgment work for you. The rate at which purchases drop out during the pause is remarkably consistent, and the savings, tracked or not, accumulate.
Pruning Regretful Categories
Smart spenders tend to audit their spending in categories, not transactions. This is the other quiet discipline. Most household budgets produce recognizable patterns in which money leaks into a few categories that don’t give much back.
Looking back over six months of bank statements tends to reveal several. The gym membership used twice. The streaming service that hasn’t been opened since February. The app subscription renewed automatically for seven months without a single login. The purchased food that becomes waste.
Each of these, individually, is a small amount. In total, across a household, they often represent a meaningful sum. Canceling three or four invisible subscriptions is rarely felt as deprivation, and yet it returns a surprising amount of monthly money.
The habit here is not to become obsessed with canceling subscriptions. It is to look honestly at whether each regular decline is giving back. If a service is being used and enjoyed, keep it without guilt. If it’s a silent drain, the honest month to cancel was probably five months ago.
The Cost-Per-Use Reframe
A lightly hidden habit of smart spenders is a simple ratio that rarely gets discussed: cost per use. For any durable item, the purchase price matters less than the number of times it will be used.
A sturdy kitchen knife that costs $200 and is used five thousand times costs less per use than a $40 knife used thirty times before rusting. A well-made pair of daily shoes that holds shape over four winters costs less per wear than three cheaper pairs that each last one season. The same is true of furniture, tools, hobby equipment and professional-grade work items.
This is not a universal argument for expensive purchases. Plenty of pricier items are as rarely used as cheap ones, and for those the reasonable response is to not buy them at all. But for the items that sit at the centre of daily life, it’s worth shifting the instinct from lowest-price to best-value-over-time.
This habit pairs naturally with the pause: when considering a non-essential purchase, ask how many times it will be used. The honest answer filters out a surprising amount.
The Small Money That Isn’t Small
Another habit of people who manage money well is adding up the small leakages that feel too trivial to notice. A coffee from a shop every weekday is a recognized habit, and people usually weigh it consciously either way. But the small purchases that pass under the radar are the ones that quietly accumulate.
The $4 magazine at the supermarket checkout. The $7 wrapper meal added to a grocery order because it was next to the queue. The $3 app purchase made because it solved a moment’s boredom. Each is trivial in isolation. Across a month, they often add up to a sum worth noticing.
The habit here is not to eliminate these purchases. It is to notice them. Many of them are invisible because they sit alongside larger purchases, and only become clear when they are grouped. A weekly tally of these tiny purchases, for one month, usually produces a low-grade surprise.
Some households put the sum of these small purchases toward one specific line item at the end of the month: a donation, a savings contribution, a treat for the family. The habit shifts from regret at small spending into satisfaction at intentional intention.
Turning Saving Into a Default
A crucial difference between people who save easily and people who struggle is not the amount they save. It is whether saving is the default or the exception.
This is the value of automation. A scheduled transfer that pulls a small set amount from the spending account into the savings account each payday, before any other spending happens, builds a habit over time. Money taken automatically is not given up; it is simply not there to be spent.
There is a useful habit of layering this with a gentle sweep. At the end of each week, look at the spending account. Whatever remains above a comfort buffer is swept into savings. The amount might be forty dollars or four hundred. The habit of sweeping the remainder, rather than spending it before the next payday, produces a slow accumulation that builds momentum.
The larger point is that saving needs to happen by default. If saving is the work you always plan to do later, after spending is sorted, it rarely happens at all.
The One-Week Survey of Every Subscription
A practical, non-deprivational exercise is to spend one week tracking every digital and physical subscription, and to check at least twice whether each one has been used in the last month.
The process usually produces two cancellations before the weekend is over. Sometimes it produces more. The surprising result is not just the money recovered but the sense of relief at not paying for digital clutter. A canceled app that was sitting on the phone unused, quietly renewed for months, carries a psychological cost on top of the financial one. Removing it frees two things at once.
This audit, done two or three times a year, is a small habit that prevents drift. Subscriptions are designed to be forgotten; this is how they accumulate. A periodic honest survey brings them back into view.
Spending With Purpose, Not Guilt
A mistake people make when they begin to spend more thoughtfully is to push guilt into the equation. Smart spending is not about remorse over every purchase, and it is not about refusing pleasure. It is about spending that matches priorities.
Some purchases are explicitly worth making. A good coffee shared with a friend might be the best $8 of the week. A well-chosen gift for someone you love. A tool that you’ll use every day. These are not expenses to regret. They are aligned spending, and aligned spending is what the whole habit system is ultimately for.
The goal of smart spending habits is not to suppress consumption but to let consumption serve life with more attention. The coffee shop that is engaging work space and good company pays back. The nameless box of daily membership renewals does not.
The point is not to eliminate small pleasures but to make sure the pleasure is actually the point of the purchase.
The Compounding Effect of Small Habits
The reason these habits work is that they are small enough to keep. Austerity programs fail because they require too much willpower. Small habits succeed because they ask for a small consistent decoding at each point of decision. Once they become routine, they stop feeling like sacrifices and start feeling like sanity.
The compounding takes a few forms. There is the literal compounding of money saved, invested, or simply kept from going to waste. There is the behavioural compounding of getting used to a mildly more considered pattern of spending, which feels easier and more natural over time. And there is the emotional compounding of feeling quietly on top of money, rather than quietly behind it.
When people describe their best financial habits, they rarely point to a single decisive budget. They point to the accumulation of small moves that, together, reshape their financial life. The weakly squeezed here and there, gently, each year, adds up to a different kind of life.
Smart spending is not a plan you implement once. It is a set of daily defaults that quietly comp on your behalf.
The Listening Market explores everyday money habits worth keeping. This piece is part of an ongoing series on practical household economics.